Chime – Mobile Banking

Screenshots


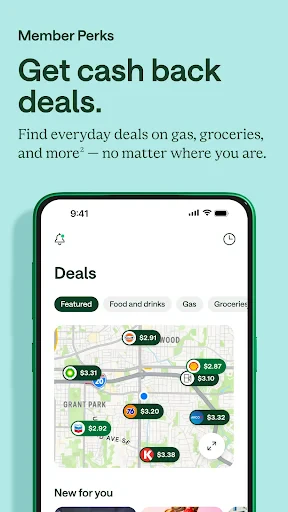

Details
- Rating
- 229.51K reviews
- Version
- 5.310.1
- Developer
- Chime
Analysis by Norviv
I usually judge a banking app by what happens when I need to check a balance quickly, move through a busy day, or sort out a small money problem—not by how polished its first screen looks. Chime – Mobile Banking is a finance app from Chime that aims to make everyday banking manageable from a phone. It is free to download, has an Everyone age rating, and has built a large audience, with more than 10 million installs and a 4.8 average from around 975,000 ratings. Those figures suggest broad appeal, but what matters most to me is whether its approach fits the way you actually handle money.
Quick access, with sensible expectations
For routine tasks, a mobile banking app should reduce friction: checking what is available, reviewing activity, and keeping an eye on payday. Chime’s appeal is strongest when you want those basics close at hand rather than having to plan a trip to a branch. I would still separate the convenience of an app from the speed of every transaction. A screen can make information easy to reach, but transfers and deposits may depend on processes outside the phone itself, so I would not build a bill-payment plan around an assumption that every step happens instantly.
Early payday can be useful if your pay arrives through a qualifying setup and the timing works for you, but I treat it as a possible scheduling advantage, not extra income. A practical habit is to budget around the date you can rely on, then treat an earlier arrival as breathing room. That keeps rent, utilities, and automatic payments from depending on a best-case timing scenario.
The app is currently at version 5.310.1 and requires Android 10 or later. That gives Android users a clear compatibility threshold to check before installing. If you use an iPhone, confirm compatibility in the relevant app store before relying on it; operating-system support can vary by platform. I also would not infer that a newer version automatically feels faster on every device. The useful test is whether the screens and account tasks you use regularly behave smoothly on your own phone and connection.
Seamless Banking Experience
First things first, the setup process is a breeze. I mean, who wants to jump through hoops just to get started? With Chime – Mobile Banking, all you need is your phone, and you're ready to roll. The app is clean, intuitive, and designed with the user in mind. It’s like having a bank branch right in your pocket.
One of the standout features is the fee-free banking. Yes, you heard that right. Say goodbye to those annoying monthly maintenance fees and hello to a more budget-friendly option. Plus, with over 60,000 fee-free ATMs, your cash is just a tap away. It’s a real game-changer for anyone tired of traditional banking fees sneaking up on them.
Where it fits into an everyday routine
A useful way to judge this kind of account is to picture a normal payday week. I might check the balance before groceries, see whether a recent purchase has posted, and decide what can safely go toward a bill. If money arrives earlier than expected, I would still keep the original bill schedule in mind and avoid spending that cushion twice. That small distinction makes early access helpful without turning it into a reason to run a tighter budget than I can afford.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
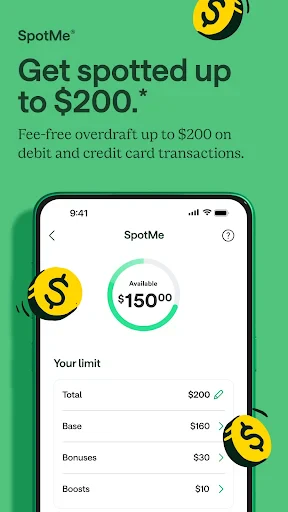
Fee-free overdraft can also matter most in an awkward, short-lived moment: a purchase clears before a deposit lands, or a small timing mismatch catches you out. I see that as a backstop, not a substitute for keeping a buffer. Eligibility and the terms that apply are worth checking in the app before counting on the feature, and I would never assume every transaction is covered in every circumstance. If avoiding overdraft risk is your priority, a separate reserve or a bank account with tools that match your habits may be a better fit.
Compared with a traditional bank app, Chime’s central trade-off is convenience built around mobile use and fewer monthly-fee concerns, rather than the feeling of a local branch relationship. Compared with a budgeting app layered over an existing bank account, it is closer to a place to manage core banking activity than simply a dashboard for accounts held elsewhere. That distinction is useful: if your main goal is to track several banks, investments, and household accounts together, a dedicated aggregation or budgeting tool may answer more of your questions. If you want a straightforward account experience on your phone, this approach makes more sense.
Budgeting Made Easy
Managing your finances can often feel like juggling flaming torches, but Chime takes the sting out of budgeting. The app automatically categorizes your spending, which is a huge time-saver. You can easily see where your money is going each month and make adjustments as needed. It's like having a personal finance assistant guiding you toward smarter spending.
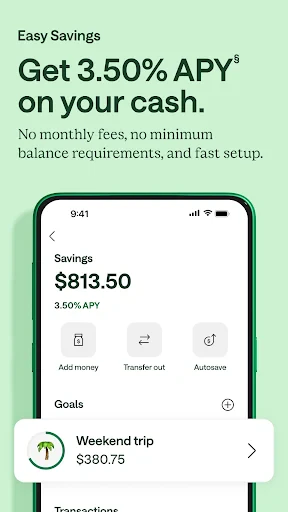
And let's talk about savings. With the "Save When You Get Paid" feature, a portion of your paycheck can be automatically transferred to your savings account. It’s a set-it-and-forget-it system that helps you build your nest egg without even thinking about it. Trust me, it’s a lifesaver for those of us who struggle with the temptation to spend.
Small habits that make the tools more useful
Automatic spending categories are a helpful first read, not a perfect accounting system. I would review unusual purchases and recurring charges rather than assuming every label tells the whole story. A quick weekly scan can reveal a subscription or a cluster of small purchases that gets lost when you only look at the month as a whole. The point is not to turn banking into a second job; it is to use the overview to decide where a closer look is worthwhile.
Automatic saving works best when the amount moved aside leaves enough for essentials and predictable bills. If your pay varies, or your expenses bunch up around a particular week, I would start cautiously and check the available balance after the transfer. The convenience is real, but a savings habit should not create a cash squeeze that forces you to move money back immediately. Treat the feature as a routine you can tune to your pay pattern, rather than a setting you never need to revisit.
That is one reason Chime may suit someone who wants a simple daily money routine more than someone who wants detailed forecasting. It can help you notice patterns and save without making every decision manually. But if you need custom categories, shared household budgets, debt payoff planning, or a consolidated picture across many financial institutions, a specialist finance app may offer more control. I would choose based on the task you need to solve, not on the assumption that one app must do everything.
Busy days, connection issues, and recovery
Heavy-use moments are usually ordinary ones: checking a balance while in line, reviewing purchases after errands, or opening the app when a payment question comes up. I value a clear route to the information I need more than extra visual effects. If the app feels slow on a particular day, first distinguish an app problem from a weak mobile connection or a transaction that is still processing. Reopening the app or trying again on a steadier connection is a reasonable first step, but I would avoid repeating a payment action until I have checked whether the first attempt went through.
For reliability, no phone app should be the only place you keep track of a critical due date or account detail. I would maintain reminders for bills separately and keep a modest cash buffer for timing gaps. If you lose access to your phone, changing devices, or cannot complete a task in the moment, having your account details and the official support route available through a trusted channel can save a rushed decision. I would also keep the app updated through the normal store process, while remembering that an update cannot fix a poor network or an issue outside the app.
Resource use is hard to judge from a product description alone, so I would not promise that it is especially light on battery, data, or storage. For an everyday banking app, I would simply watch how it behaves alongside the other apps you use and avoid relying on it over an unstable connection for time-sensitive decisions. The Android minimum is relevant if you have an older handset: a device below Android 10 will not meet the stated requirement, and replacing a working phone solely for one banking app may not be worthwhile.
Security and Support
When it comes to your hard-earned cash, security is a top priority. Chime uses top-notch encryption to keep your information safe, which definitely gives me peace of mind. Plus, if you ever misplace your card (it happens to the best of us), you can instantly disable it from the app. No more panicking or frantic calls to customer service.
Speaking of customer service, the support team is super responsive. Whether you prefer chatting in-app or shooting off an email, help is always just a click away. It's nice to know that real humans are ready to assist whenever you need them.
Who should choose it—and who might not
I can see this being a good fit for someone who wants mobile-first banking, values avoiding monthly fees, and would make regular use of early payday or a fee-free overdraft safety net. It may also suit a person who finds automatic saving easier than remembering to transfer money manually. Chime is less compelling if your banking depends on a branch, if you need a sophisticated multi-account planning workspace, or if your phone does not meet the operating-system requirement. Anyone depending on a particular overdraft or deposit feature should read its current terms and eligibility details before making it part of a budget.
The app is free, but I would still think beyond the download price when comparing accounts. Check the terms for the services you expect to use, look at how cash access works for your routine, and consider whether its mobile-centered setup fits your habits. A no-monthly-fee approach can be valuable, yet the best choice is the one whose practical details line up with how you receive income, pay bills, and handle cash.
My performance verdict
Chime is at its most convincing as a practical daily banking companion: it puts useful money tasks in one mobile experience and pairs them with options aimed at reducing common fee and timing frustrations. I would not judge reliability by a single fast or slow session, and I would keep a backup plan for important payments rather than expecting an app to remove every real-world delay. With those expectations, it has a clear role for people who want simple mobile banking and a less suitable one for people who need branch access or extensive financial planning tools.
So, if you're looking for a banking app that's straightforward, reliable, and packed with features tailored to making your financial life easier, Chime – Mobile Banking might just be your new best friend. It's the perfect blend of modern convenience and smart money management. Give it a whirl and see if it fits your lifestyle. Your wallet might just thank you!
Frequently Asked Questions
01What are the main features of Chime – Mobile Banking?
Chime offers a variety of features designed to make banking convenient and accessible. Users can enjoy no-fee overdraft protection, early direct deposit, and a high-yield savings account. The app also provides instant transaction alerts, easy money transfers, and a robust security system to protect your financial data.
02Is Chime – Mobile Banking safe and secure to use?
Yes, Chime prioritizes the security of its users. The app uses 128-bit AES encryption to protect your data. Additionally, Chime is FDIC insured up to $250,000 through its banking partners. The app also provides real-time transaction alerts to help you monitor your account for any unauthorized activity.
03Does Chime charge any fees for its services?
Chime is known for its no-fee banking model. There are no monthly maintenance fees, no minimum balance fees, and no overdraft fees if you qualify for SpotMe. However, there may be fees for out-of-network ATM usage or transactions involving foreign currencies. It’s advisable to check their fee schedule for detailed information.
04How does Chime's early direct deposit feature work?
Chime’s early direct deposit feature allows you to access your paycheck up to two days earlier than traditional banks. Once your employer submits payroll information, Chime makes the funds available to you as soon as they receive them. This can provide timely access to your money and help manage expenses more efficiently.
05What should I do if I encounter issues with my Chime account?
If you experience any problems with your Chime account, customer service is available to assist you. You can reach out through the app, contact them via phone or email, or visit their support page for quick resolutions. Chime also provides a comprehensive FAQ section on their website for common concerns.


